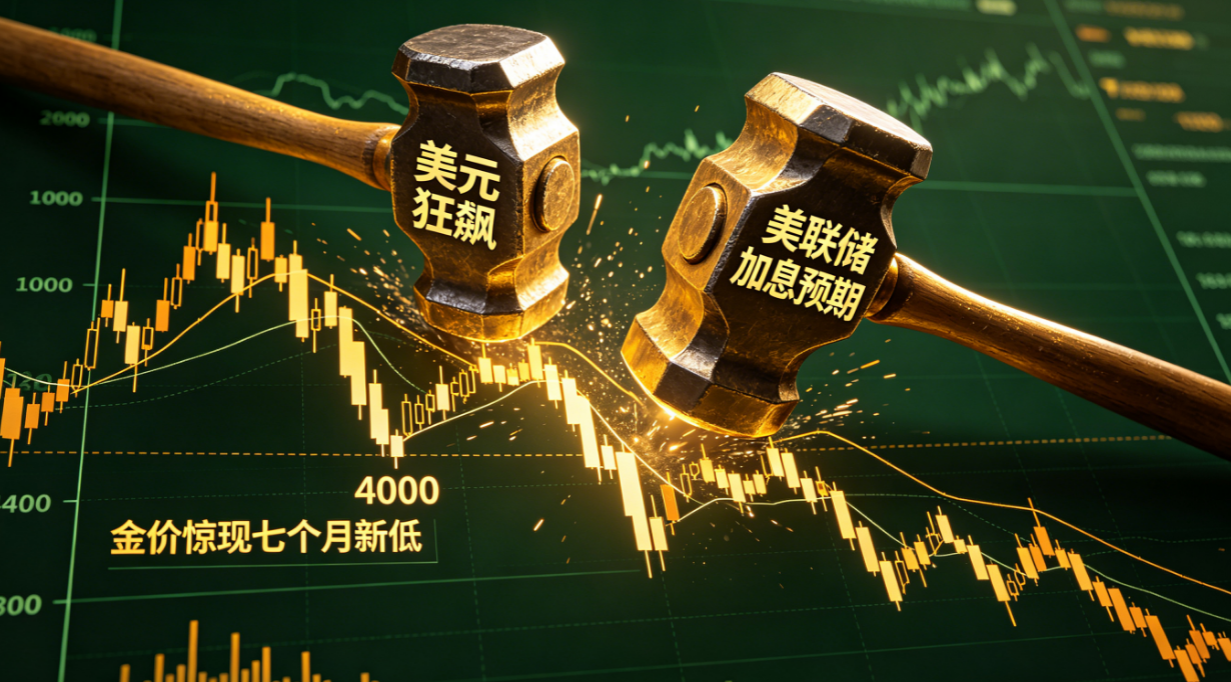
A dramatic turning point is unfolding in the global gold market. On Wednesday (June 24), spot gold plunged 2.7%, closing at $3,998.95/oz, breaking below the key $4,000 psychological level and hitting a seven-month low. Earlier, it touched a low of $3,959.04/oz, the lowest since Nov 2025. This sharp decline caught long gold investors off guard, who had been at historical highs earlier this year, triggering a reassessment of precious metals' long-term outlook. Amid a strong US dollar rebound, rising Fed rate hike expectations, and easing geopolitical tensions, gold's safe-haven allure has temporarily dimmed. On Thursday (June 25) early Asian session, spot gold traded narrowly around $4,000, currently near $3,995/oz.
Current brutal market moves: Rapid descent from highs to abyss
Gold's decline has been exceptionally swift. US gold futures also slumped 3.4% to close at $4,008.80. Just a few months ago, spot gold hit an all-time high of $5,596 in late January, and has since fallen over $1,600. This sharp correction tests investor nerves and highlights rapid shifts in market sentiment. Other precious metals fared worse, with spot silver tumbling 6.7%, hitting a new low since Nov 2025, indicating broad selling pressure across the precious metals sector.
Investors quickly turned their focus to the macro level. A strong dollar became the direct trigger for gold's collapse—when the dollar index rose to a 13-month high near 102, dollar-denominated gold became more expensive for other currency holders, dampening demand.
Dollar and hawkish Fed signals: gold's biggest killer
The dollar's strength is no accident. Since the Fed's policy meeting last week sent a clearly hawkish signal, market expectations for a rate hike this year have risen significantly. Traders are preparing for a possible rate hike in July or September, with the probability of a September hike climbing to around 66%. Fed officials' comments reinforced this expectation: with the economy seemingly solid, the policy focus is shifting towards curbing inflation rather than merely supporting growth.
Independent metals trader Tai Wong noted that the Fed's hawkish stance, the dollar's rise to a 13-month high, and falling inflation expectations have put heavy pressure on precious metals. Higher interest rates directly weaken gold's appeal, as non-yielding assets become more costly to hold in a high-rate environment. Analysis from Barclays also shows mild buying signals for the dollar at month-end, and despite some sell signals from quarterly models, the dollar's near-term strength is unlikely to reverse.
Meanwhile, tech stock selling in US markets indirectly boosted the dollar's safe-haven status. Investors await Thursday's US personal consumption expenditures (PCE) inflation data, the Fed's preferred gauge. A stronger-than-expected reading could further support rate hikes, keeping gold's downside risk alive.
Geopolitical easing and oil price crash: safe-haven demand plummets
Gold's collapse is also closely tied to an unexpected easing of geopolitical tensions. The preliminary peace agreement between the US and Iran is gradually releasing oil supply that had been pent up due to tensions in the Strait of Hormuz. More tankers are leaving the strait, causing Brent crude to fall over 3% and US crude to drop below $70/bbl, its lowest since the conflict began. Falling oil prices ease inflation concerns and reduce gold's appeal as an inflation hedge.
US Secretary of State Rubio's shuttle diplomacy in the Middle East seeks to reassure Gulf allies, while technical talks are set to resume in Switzerland at the end of the month. Although Israel insists on keeping troops in southern Lebanon and Iran voices criticism, overall, the cooling of regional tensions has significantly reduced gold's safe-haven premium. Fears that an Iran conflict could push inflation higher are fading, replaced by optimism about supply recovery.
Expert views and institutional adjustments: support remains, but rebound takes time
Despite short-term pressure, the market is not entirely pessimistic. Tai Wong believes there is some support for gold below $3,900, and the trend of global central banks continuing to buy gold is unlikely to change easily, making a crash unlikely, but gold may enter a longer consolidation phase. Standard Chartered's analysis of silver is similar: although short-term outflows cause volatility, supply shortages suggest a possible rebound in the coming months.
ING analysts have cut gold price forecasts, lowering the Q3 2026 average estimate from $4,850 to $4,300 and Q4 from $5,000 to $4,600. This adjustment reflects a rapid response to changing macro conditions. However, US inventory data still shows crude oil inventories at historical lows, with strong refinery demand, which could provide some support for inflation in the future, indirectly affecting gold.
Looking ahead: can gold regain its uptrend?
Overall, gold is at a critical turning point. Fed policy uncertainty, the dollar's strong momentum, and supply release from geopolitical easing all create short-term downward pressure. Thursday's PCE data will be a key indicator; if inflation data is moderate, it could temporarily ease rate hike expectations; otherwise, gold may face further pressure.
From a medium- to long-term perspective, central bank buying, potential geopolitical risks, and global economic uncertainty still provide structural support for gold. Investors should monitor the Fed's next moves, the implementation of the Iran agreement, and oil price trends. In the current environment, gold may not quickly return to highs, but it may not fall indefinitely—near $3,900 could be an important test.
This round of gold adjustment is both an inevitable result of macro factors and a correction of overly optimistic expectations earlier. No matter how volatile in the short term, gold's strategic value as a key part of global asset allocation has not disappeared. Investors need to remain rational and wait for clear signals amid the turbulence.