Deep Adjustment in Precious Metals Market: Logic Behind Gold and Silver’s Joint Fall and Outlook
Keywords: Precious metals, gold, silver, safe-haven assets, Federal Reserve, US dollar index, market adjustment, investment strategy
Introduction
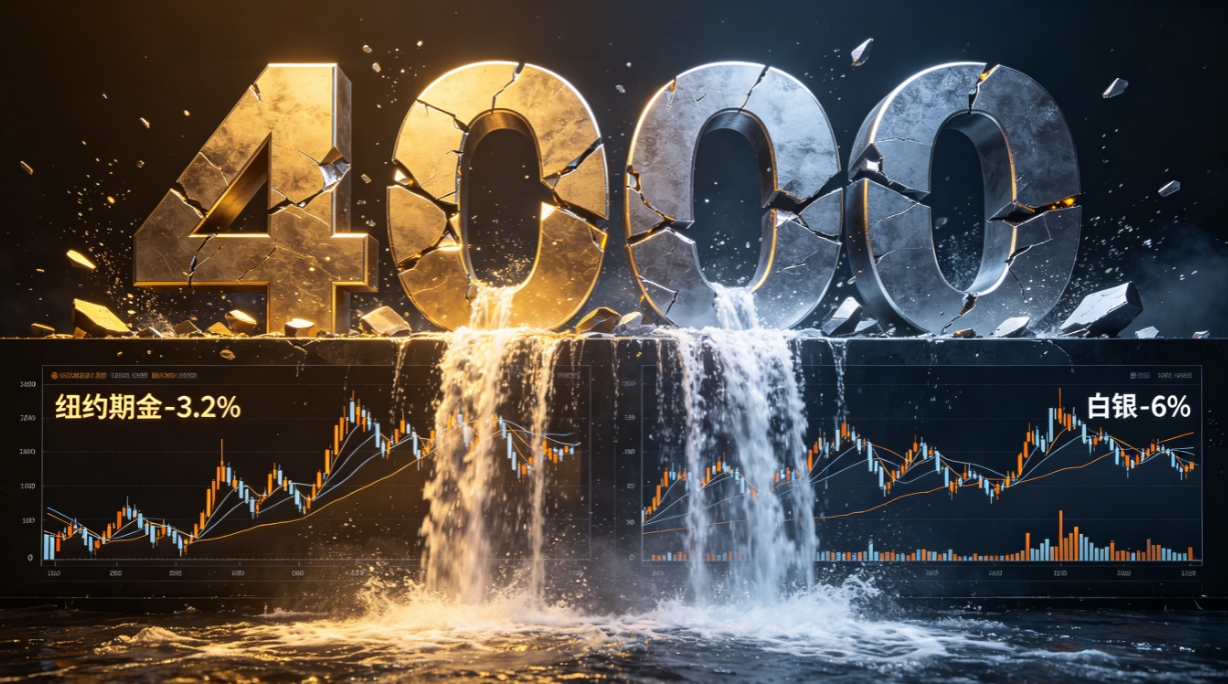
Recently, the precious metals market has experienced notable volatility, with gold and silver weakening simultaneously, shifting market sentiment from strong optimism to cautious watchfulness. Especially after running at high levels for a time, gold lost key integer levels, while silver’s decline intensified, indicating that the precious metals sector has entered a phase of periodic adjustment. For investors, this is not only a price pullback but also a concentrated repricing of the macro environment, fund flows and market expectations.
I. Why Precious Metals Suddenly Came Under Pressure
Precious metals are known as "safe-haven assets," and their prices are usually closely related to global uncertainty, monetary policy expectations and the dollar trend. This gold and silver correction is not caused by a single factor but the result of multiple variables superimposed.
First, from a macro perspective, market expectations for the Fed's rate cut path have adjusted. If the market previously generally bet on rapid easing, once such expectations are postponed, precious metals come under pressure due to rising holding costs. Gold itself does not generate interest income, so when the interest rate environment is high or the timing of rate cuts is pushed back, funds tend to flow to yield-generating assets like bonds or cash.
Second, the phase-based strength of the US dollar index also puts pressure on dollar-denominated precious metals. A stronger dollar means higher purchase costs for non-dollar holders of gold and silver, naturally dampening demand. Meanwhile, a recovery in risk asset sentiment weakens precious metals' safe-haven appeal.
Finally, technical factors cannot be ignored. After gold traded at high levels for an extended period, once key support levels were broken, it triggered concentrated exits from algorithmic trades, stop-loss orders, and short-term profit-taking, leading to a rapid pullback.
II. Gold Losing Key Levels: What It Means
Gold prices breaking below key integer levels often carry strong market psychological significance. Integer levels are not only reference lines that investors commonly watch but also important battlegrounds for bulls and bears. When gold holds a certain key level, the market reinforces upward expectations; conversely, once lost, it may trigger a reassessment of trend sustainability.
From a medium- to long-term perspective, gold still has monetary, reserve and risk-hedging attributes. Central banks around the world continue to increase gold holdings, reflecting a shift in global asset allocation towards higher safety. Especially against the backdrop of geopolitical uncertainty, fiscal deficit pressures and high global debt, gold’s strategic allocation value remains undiminished.
However, in the short term, gold prices act more like a "sensitive responder" to expectation changes. When market judgments on rate cuts, inflation and safe-haven demand change, gold will reflect these subtle differences first. Therefore, the current decline does not necessarily mean that gold’s medium- to long-term logic is broken; it is more likely a technical correction and expectation rebalancing after earlier gains.
III. Silver’s Larger Decline: Signals
Compared to gold, silver typically exhibits more volatile movements because it has dual attributes of both a precious metal and an industrial metal. On one hand, silver also has safe-haven functions; on the other hand, its price is affected by the manufacturing cycle, photovoltaic demand and the electronics industry. Therefore, when macro expectations weaken or industrial demand expectations are revised down, silver is often more sensitive than gold.
The significantly larger decline in silver this time indicates that the market still has doubts about the global economic growth outlook. If manufacturing expansion momentum is insufficient, silver’s industrial demand cannot provide strong support; and when safe-haven sentiment recedes, silver struggles to rely solely on its precious metal attribute for independent upward momentum. Thus, its price often exhibits larger oscillations under multiple pressures.
For silver investors, this means that gold logic cannot be simply applied to judge silver’s trend. Silver’s high elasticity brings greater profit potential but also higher risk exposure. Without position management and stop-loss mechanisms in investment, one can easily suffer large losses during sharp declines.
IV. Core Variables for Precious Metals Outlook
Looking ahead, the precious metals market will continue to revolve around the following core variables:
First, monetary policy pace. Whether the Fed starts rate cuts and whether the magnitude is above expectations will directly affect gold’s opportunity cost. If future data supports a dovish turn, precious metals may regain support.
Second, dollar and real interest rate trends. Real interest rates are an important factor in gold pricing. If inflation falls faster than nominal interest rates, real rates may remain relatively high, thus suppressing gold performance.
Third, geopolitical and risk events. Once global tensions escalate again, gold’s safe-haven buying typically returns quickly, driving price recovery.
Fourth, physical demand and central bank gold purchases. Gold jewelry consumption, investment bar demand and ongoing central bank buying form the medium- to long-term fundamental support for gold. For silver, industrial demand recovery, especially in new energy and photovoltaic supply chains, needs close monitoring.
V. How Investors Should Navigate Current Volatility
Against the backdrop of increased precious metals volatility, the most important thing for investors is to avoid emotional chasing of rises and selling on falls. In the face of adjustments, strategies should focus more on layered allocation and risk control.
For long-term allocation investors, precious metals can still serve as a "stabilizer" in the portfolio, but should not be heavily bet on a one-sided trend. A more reasonable approach is to use phased building and dynamic rebalancing, treating gold as a hedging tool rather than a short-term speculative instrument.
For short-term traders, the current increased market volatility significantly raises the risk of chasing orders. More attention should be paid to key support and resistance zones, with strict stop-loss and take-profit settings to avoid magnifying pullbacks due to high leverage.
For silver investors, due to its typically higher volatility than gold, position control is even more critical to avoid being caught in repeated "sharp decline-rally-sharp decline" washouts during periods of liquidity contraction.
Conclusion
Overall, the current correction in the precious metals market is both a result of changing macro expectations and a natural correction after earlier gains. Gold losing key levels reflects a repricing of the rate path and dollar trend; silver’s larger decline highlights its high sensitivity to the economic cycle and industrial demand.
But from a longer time dimension, the core value of precious metals has not changed. Whether it is gold’s monetary attribute or silver’s dual attribute, both determine their irreplaceable role in asset allocation. For investors, what really matters is not the decline itself, but the ability to identify trends, manage risks and grasp allocation rhythm amid volatility. In the future, the precious metals market will continue to revolve around policy, the dollar, inflation and safe-haven sentiment, and rationality and patience will remain key to navigating the waves.